You’re about to launch or are in the early startup stage, and you need a home for your new business. You also need a startup loan to finance your dream. But you need to determine the right time to sign a business lease. Should it be before, during, or after applying for a small business loan? Does it matter?
In fact, it could matter a lot! In this guide, you’ll learn the best strategy and steps to take for signing a business lease when applying for startup financing.
Why does it matter when you sign a business lease for startup financing?
Signing a business lease for your startup should show that you’ve thought through your plans, researched the right location, and put in the effort to find the perfect spot for your business. And yet, there are reasons why a lender may not want you to sign a lease before getting loan approval and closing on financing.
Here are some reasons:
1. Signing a lease too early can obligate you at the wrong time
If your application isn’t approved or the loan process takes longer than expected, you’ll still be responsible for any obligations that have taken effect under the lease, which may include rent, security deposits, insurance, utilities, and other lease-related costs. This could strain your finances before you have the funding needed to complete the project and open your business.
2. Renovations can reshape the entire project
A space may look like the right fit, but renovations or leasehold improvements can quickly change the cost and scope of your project. Your lender will need to understand the work involved, the expected cost, and whether you or the landlord will be responsible for completing and paying for it. Signing the business lease before financing is approved could leave you committed to a location or project that no longer fits the approved loan amount or overall budget.
3. A great location still needs to fit the numbers
A space may look like the perfect home for your business, but the rent is only one part of the overall project. Before approving the loan, the lender will need to review the lease terms, monthly occupancy costs, buildout needs, and total project budget. Signing too early could lock you into a location that no longer fits the financing available or the project as approved.
These are some of the key reasons why lenders will caution small business owners in the startup phase to hold off on signing a business lease until after financing is secured.
Still, as part of the loan process, you need to identify a location for your business. So, what should you do?
How to secure a business lease for your startup loan
To get the loan you need without putting your finances at risk, here’s the recommended strategy for startup businesses:
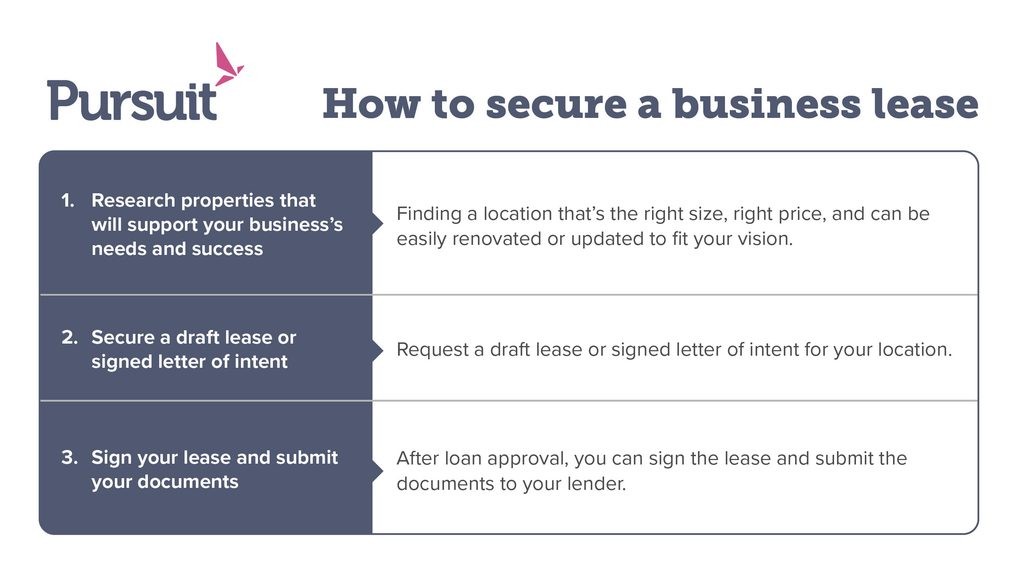
1. Research properties that will support your business’s needs and success
This means finding the right location, a space that’s the right size and, when possible, that’s relatively easy to renovate or update so that it suits your vision without overcommitting you financially.
2. Secure a draft lease or signed letter of intent
Once you’ve found an ideal location, ask the landlord for a draft lease or signed letter of intent (LOI). These documents show you identified a viable location without committing to a final lease too early. They also provide your lender with the key terms needed for underwriting, including the lease term, monthly rent, security deposit, anticipated renovations or leasehold improvements, and who’s responsible for completing and paying for any renovations.
- A draft lease is a proposed lease document that outlines the expected terms but hasn’t been fully executed yet.
- An LOI is a document signed by the borrower and the landlord that summarizes the key proposed terms such as location, rent, length of the lease, the required deposit, and any renovation expectations, as well as who is responsible for those.
3. Sign your lease and submit your documents
When your loan is approved and ready to close, you can sign the lease and submit the documents to your lender as part of your loan-closing process. These steps can help you secure the location you want for your business, while minimizing your financial risk.
Discover the Top Tips Before Signing Your Lease Agreement in the video below.